Wall Street loves a tidy narrative. Take a dominant player in an overlooked market, slap a shiny nine-figure initial public offering price tag on it, and watch the analysts nod in unison. The recent chatter surrounding Transsion eyeing a five hundred million dollar capital injection in Hong Kong follows this exact script. Financial media frames it as a triumphant march by Africa's reigning smartphone kingpin, poised to fund its next phase of global expansion.
It is a comfortable story. It is also completely backwards. For an alternative view, consider: this related article.
I have spent the last decade watching hardware giants hemorrhage capital trying to replicate emerging market playbooks in mature zones. Transsion did not conquer sub-Saharan Africa by accident; they won because they mastered hyper-local engineering, from multi-SIM architecture suited for fragmented carrier grids to camera sensors calibrated specifically for darker skin tones. But raising half a billion dollars in Hong Kong to fuel an assault on higher-end markets misses the entire structural shift happening beneath their feet.
The lazy consensus says Transsion is bulletproof because their volume is massive. The reality is that volume without margin is just an expensive logistics exercise. Further analysis on this trend has been published by Reuters Business.
The Margin Trap Nobody Wants to Talk About
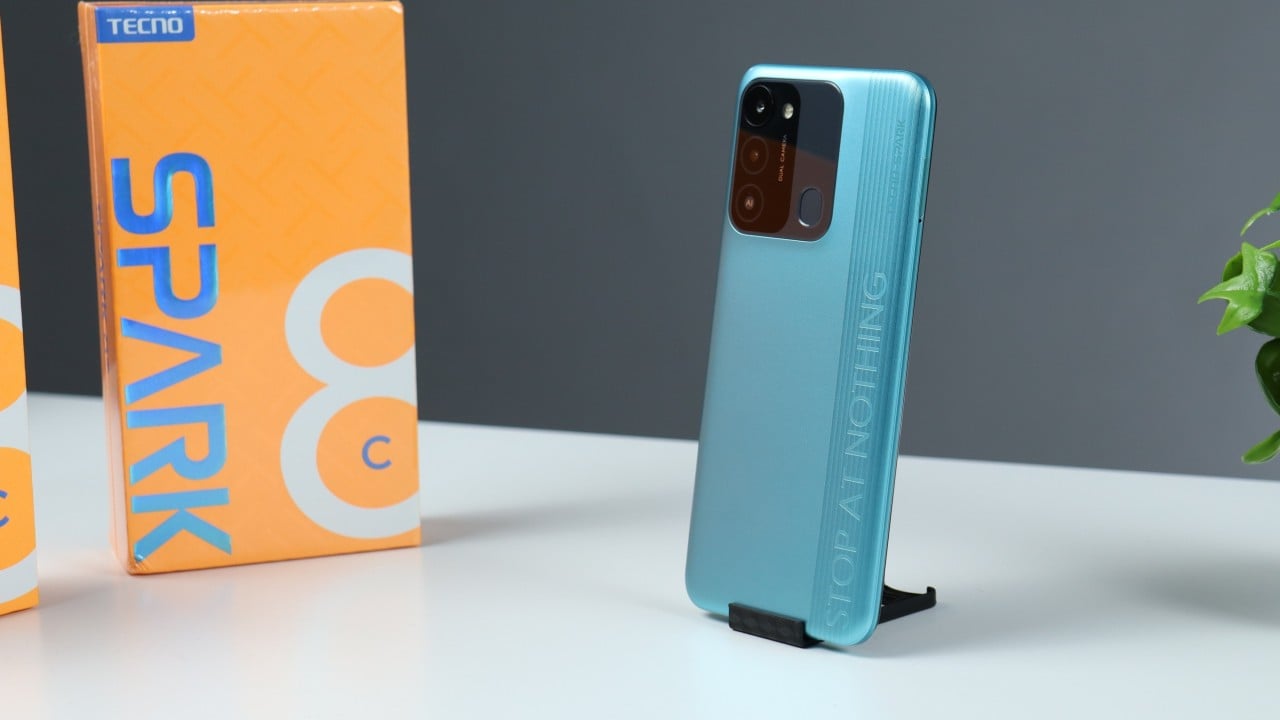
Look at the unit economics of a ninety-dollar smartphone. After component costs, localized software licensing, distribution bribes in chaotic port cities, and aggressive retail incentives, the breathing room is razor-thin. Transsion built an empire on cheap, reliable hardware sold to consumers who are upgrading from feature phones for the very first time.
That well has a bottom.
When you raise five hundred million dollars through public markets, public shareholders do not want steady single-digit margins in developing regions. They want hyper-growth. They want software monetization, cloud services, and premium hardware penetration. They want you to fight Apple and Samsung on their home turf.
That is financial suicide.
If Transsion tries to pivot upstream into four-hundred-dollar devices to appease public market analysts, they step directly into the meat grinder of the Chinese domestic market, where Xiaomi, Oppo, and Vivo already wage a brutal war of attrition. If they stay put, the growth curve flattens. The Hong Kong listing is not a weapon of conquest; it is a liquidity event designed to provide an exit hatch for early private equity backers while shifting the existential risk onto retail investors.
Software Is Not Your Savior
Every time a hardware manufacturer hits a margin wall, management reaches for the oldest buzzword in the playbook. They promise investors that the real money lies in services, digital wallets, and advertising revenue stitched into the operating system.
It sounds great in a slide deck. On the ground in Nairobi, Lagos, or Karachi, it fails basic economic reality.
Data is expensive. Disposable income is constrained. Users download utility apps when they need them and delete them when internal storage runs low. The idea that you can bolt a high-margin fintech or media ecosystem onto a population whose average revenue per user hovers in the single digits monthly is a fantasy concocted by executives who have never run a credit check in a cash-first economy.
Transsion's proprietary operating systems, like HiOS and XOS, are exceptional at delivering lightweight performance on cheap silicon. They are not revenue-generating ad networks. Trying to squeeze advertising dollars out of a customer base that counts every megabyte of data is a fast way to destroy brand loyalty.
The Real Threat Is Not Apple
Analysts love to frame this battle as David versus Goliath, with Transsion as the scrappy insurgent upending Western titans. That framing is ten years out of date.
The real pressure comes from localized Chinese competitors who have looked at Transsions playbook, stripped away the overhead, and are now manufacturing hardware so cheap that it defies traditional supply chain logic. Furthermore, the used and refurbished smartphone market has matured into an industrial-scale beast. A high-end Samsung or Apple device from three years ago, resold in top-tier African urban centers, offers vastly superior performance, camera fidelity, and social status compared to a brand-new entry-level device.
A consumer does not care about your corporate mission statement when a secondhand flagship with a replaced battery lasts twice as long and runs heavier applications without stuttering.
The Five Hundred Million Dollar Question
If you are deploying capital into this IPO, you are betting that management can successfully navigate a triple constraint: defending low-end volume against ruthless regional copycats, avoiding the margin-crushing trap of premium hardware expansion, and proving that software monetization works where every precedent says it does not.
That is not a growth story. That is a tightrope walk over an active volcano.
Hype dies when the quarterly earnings reports land and currency devaluations across key operating regions chew up operating income. A war chest of cash does not invent consumer purchasing power out of thin air.
Stop cheering for the ticker symbol and start looking at the balance sheet.