The neon signs of Causeway Bay and Tsim Sha Tsui have always flickered with the ambition of outsiders, but something heavier is shifting in the SAR's commercial arteries. While local landlords grapple with stagnant domestic consumption and an exodus of outbound weekend shoppers heading north to Shenzhen, a counter-intuitive wave of foreign flagships is washing ashore. Japanese, South Korean, and Thai brands are aggressively planting flags across Hong Kong's most expensive retail corridors. This is not a casual seasonal trend. It is a calculated, high-stakes repositioning driven by desperate commercial real estate landlords, shifting Asian consumer loyalties, and a fundamental recalculation of Hong Kong's viability as a regional showcase market.
To understand why foreign chains are flooding into a market widely reported to be in retail distress, you have to look past the gloomy headlines about local spending habits. Landlords are bleeding. Commercial vacancy rates in core districts forced rents down from their stratospheric 2019 peaks by forty to sixty percent in many prime locations. For an emerging fashion label from Seoul or a specialty lifestyle concept from Bangkok, Hong Kong was once a financial impossibility. Today, it is an accessible entry point to global exposure at a steep discount.
The primary driver behind this influx is the first-store appeal. In an era where online shopping commoditizes everything from streetwear to skincare, physical retail survives exclusively on theater and exclusivity. Asian brands from neighboring hubs recognize that Hong Kong consumers and mainland tourists alike treat novelty as currency. When a popular South Korean aesthetic brand or an artisanal Thai cafe opens its inaugural Hong Kong location, it triggers a massive wave of social media validation. Queues stretch around blocks not merely because people want a product, but because they want to broadcast their presence at the epicenter of the trend.
The Real Estate Calculation
Commercial landlords in prime districts like Central, Causeway Bay, and Mong Kok are no longer holding out for luxury mega-conglomerates willing to sign ten-year leases at record-breaking valuations. Those days are gone. Instead, property portfolios are pivoting toward curated curation. Landlords are offering flexible terms, revenue-sharing models, and tenant improvement allowances that would have been unthinkable a decade ago.
This financial flexibility lowered the barrier to entry for mid-tier international brands that previously lacked the war chest to absorb multi-million dollar deposits. A Thai lifestyle brand or a boutique Japanese cosmetics firm can now test the waters with a pop-up or a compact flagship without betting the entire company's balance sheet on a single lease.
Yet, this dynamic reveals a stark division within the city's commercial ecosystem. While international chains are securing prime real estate under favorable terms, local independent merchants face a brutal reality. They do not enjoy the cross-subsidies of an established foreign parent corporation, nor do they command the immediate marketing buzz that an exotic overseas import generates. The influx of Japanese, South Korean, and Thai competitors is oxygen for the landlords, but it is suffocating the indigenous retail fabric that once gave Hong Kong neighborhoods their unique grit.
Consumer Psychology and the Cross-Border Paradox
Hong Kong residents are currently participating in a massive behavioral paradox. Tens of thousands of locals cross the northern border every weekend to spend their disposable income in Shenzhen and Guangdong, chasing lower prices, larger service spaces, and novel entertainment concepts. Critics argue this hollows out the local economy.
However, the same consumers who spend Saturdays hunting for cheap dining and entertainment in mainland China return to Hong Kong demanding global trend status. They want international experiences without the flight ticket. Japanese food concepts, South Korean streetwear labels, and Thai design houses satisfy this craving for cosmopolitan identity. They offer a psychological buffer against the feeling that Hong Kong is losing its international edge.
Tourists from Southeast Asia and mainland China also factor heavily into this equation. For mainland visitors, Hong Kong's retail landscape has evolved. The days of hauling back dozens of luxury status symbols are being replaced by a preference for niche lifestyle goods, experiential dining, and discoverable aesthetic brands. A unique Thai design concept store or a cult-favorite Japanese matcha house provides the exact kind of shareable, high-vibe experience that modern tourism demands.
Operational Hurdles Beneath the Glossy Surface
Do not mistake this retail migration for easy expansion. Operating a foreign brand in Hong Kong introduces punishing structural challenges that catch many overseas operators off guard. Labor shortages in the service and retail sectors remain chronic. Finding bilingual, highly polished floor staff who can manage both local customers and mainland tourists while maintaining brand standards is an expensive endeavor.
Furthermore, logistics and regulatory compliance present hidden friction. Import duties, strict health and safety certifications for food and cosmetics, and the sheer bureaucratic weight of setting up foreign entities in the SAR require deep local partnerships. Brands that arrive expecting an frictionless plug-and-play environment often find their margins compressed within the first six months.
Consider the logistical reality of a medium-sized Thai cafe chain entering the market. Sourcing authentic ingredients while navigating Hong Kong's stringent food safety import protocols often forces compromises on flavor or drives up supply chain costs. If the product deviates too far from the home-market standard, the core appeal evaporates. If it adheres strictly, the margins disappear beneath rent and labor overhead.
The Structural Threat to Local Identity
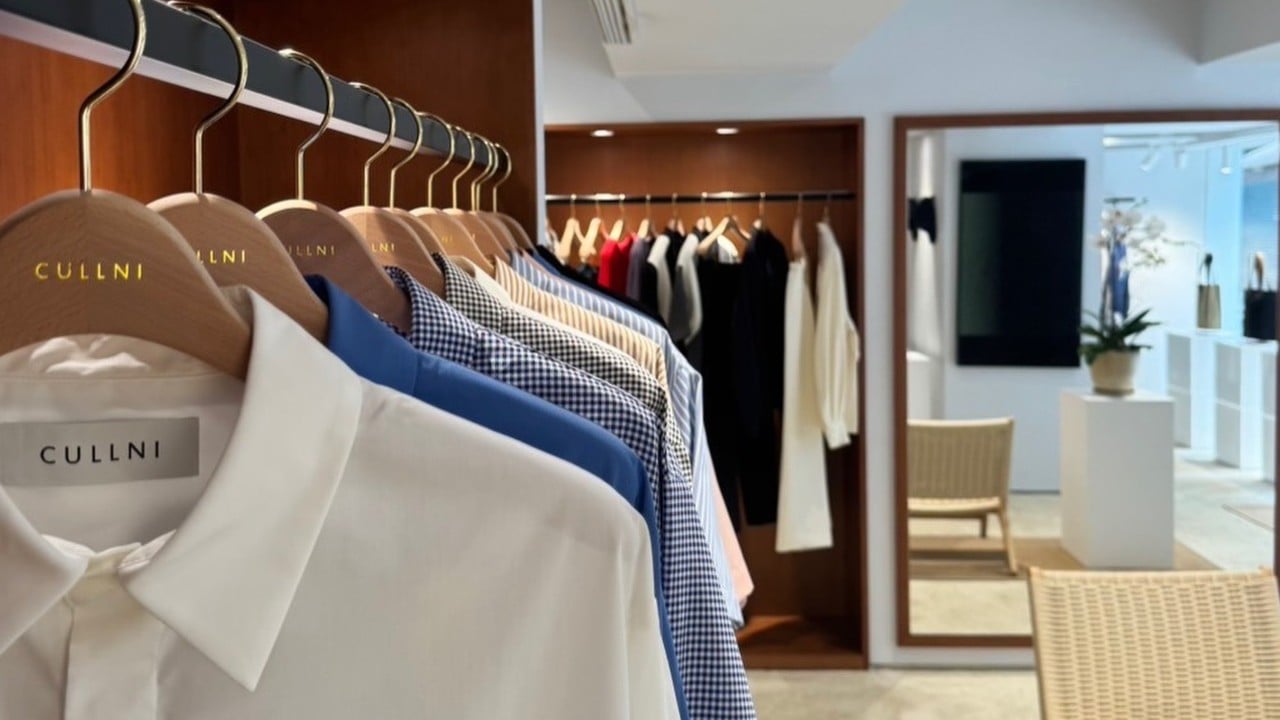
As these foreign flagships multiply, the visual vocabulary of Hong Kong's street level undergoes a quiet homogenization. The neon-lit chaos of traditional local cha chaan tengs and independent apothecaries is increasingly bookended by minimalist Seoul-style concrete cafes and pristine Tokyo lifestyle boutiques.
This transformation creates a double-edged sword for the city's tourism board. On one hand, a vibrant influx of fresh international brands proves that Hong Kong retains its magnetic pull as Asia's world city. On the other hand, it threatens to erode the very distinctiveness that made travelers fall in love with the territory in the first place. When every global metropolis features the exact same rotation of curated aesthetic brands from East and Southeast Asia, the unique friction and character of Hong Kong risk getting sanded down into a frictionless, generic international terminal.
The strategy of leaning on foreign flagships is a high-stakes gamble. It relies on the assumption that perpetual novelty can outrun the structural decline of traditional retail channels. For now, the queues outside these newly arrived stores suggest the gamble is working. But the true test will arrive when the initial wave of curiosity fades, leaving these foreign brands to contend with the same high operating costs and shifting consumer whims that broke their predecessors.
The neon keeps buzzing, but beneath the glow, the margin for error has never been thinner.