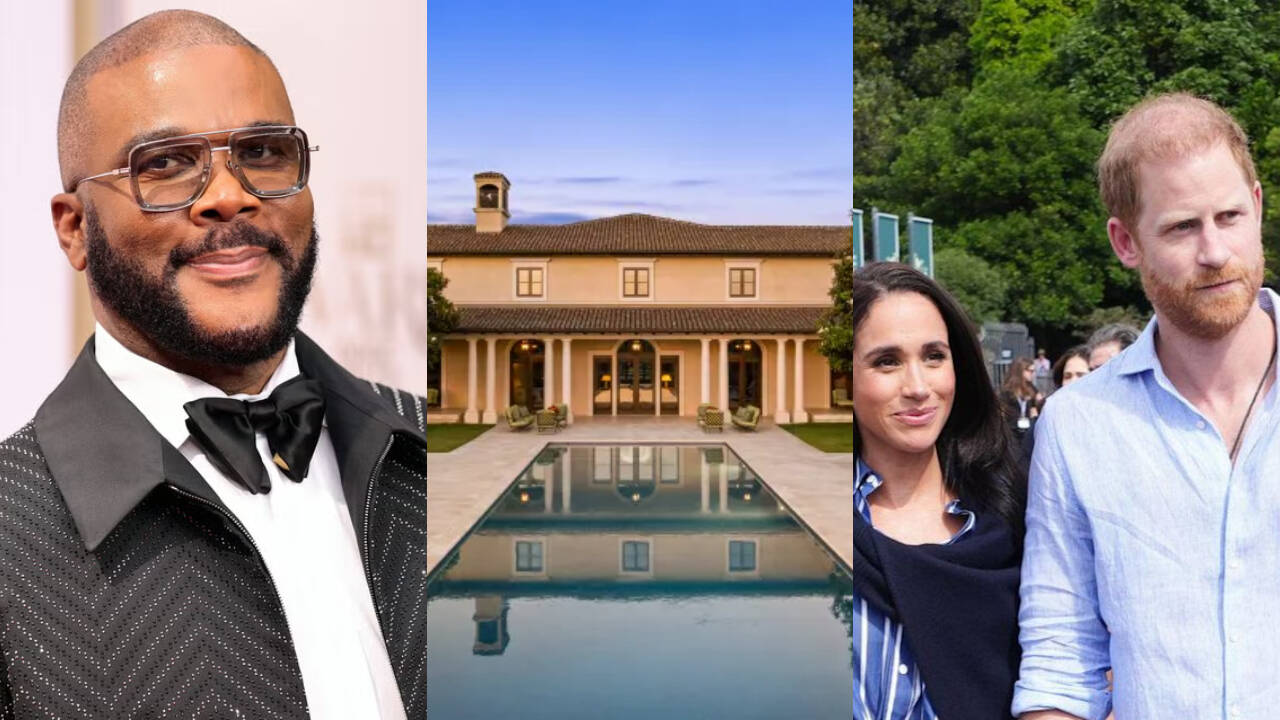
Ultra-prime real estate pricing operates on liquidity horizons entirely disconnected from traditional residential markets. When Tyler Perry listed his Beverly Hills compound for $57 million, the transaction mechanics extended far beyond a standard high-net-worth asset exchange. Understanding this valuation requires stripping away the celebrity provenance that dominated public reporting and examining the underlying capital allocation strategy, asset amortization, and spatial security economics governing properties of this magnitude.
At the apex of the residential property hierarchy, assets cease to function primarily as domestic spaces. Instead, they operate as illiquid capital stores subject to distinct carrying costs, geopolitical portfolio reallocation, and security overheads. You might also find this connected story useful: Why the JPMorgan Gay Job Lawsuit Exposes Corporate America Culture Wars.
The Capital Architecture of Ultra Prime Assets
The valuation of a $50 million-plus residential asset relies on structural scarcity and high replacement barriers rather than comparative market analysis of standard suburban housing. In the Beverly Crest and Beverly Hills Post Office micro-markets, land parcels large enough to support compound-style privacy are mathematically constrained.
- Replacement Cost Disparity: Acquiring raw acreage, securing municipal permits for massive subterranean and above-grade footprints, and managing supply chains for bespoke finishes create a cost floor that often matches or exceeds historical acquisition prices.
- Carrying Cost Mechanics: Property taxes, structural maintenance, specialized landscaping, and elite security details create an annual cash burn that forces periodic portfolio rationalization. For global billionaires, holding idle residential inventory incurs an opportunity cost relative to liquid instruments yielding baseline risk-free rates.
- Geographic Portfolio Optimization: Capital shifts—such as Perry's documented strategic pivot toward alternative jurisdictions like Puerto Rico—frequently trigger coordinated asset liquidations. Real estate at this tier is rarely sold due to localized market distress; it is sold to reallocate capital into higher-yield or more tax-efficient vehicles.
The Security Premium and Spatial Insulation
A major factor driving the historical value of the Beverly Hills estate was not merely architectural square footage, but absolute spatial insulation. For high-profile individuals facing severe external threat vectors, traditional luxury housing fails due to perimeter vulnerabilities. As extensively documented in detailed articles by Bloomberg, the implications are widespread.
Properties capable of commanding a $57 million valuation internalize the cost of enterprise-grade security infrastructure. This includes gated entry points separated significantly from main living structures, advanced electronic surveillance corridors, and private access roads that eliminate public sightlines. When Prince Harry and Meghan Markle utilized the estate in 2020, the functional utility they extracted was institutional-grade risk mitigation. In the luxury segment, the presence of these defensive systems shifts the asset demand curve upward, attracting buyers whose primary utility function is privacy preservation rather than lifestyle enhancement.
Liquidity Friction in the Eight-Figure Segment
The buyer pool for assets priced above $50 million represents an extremely narrow demographic slice globally. This creates severe liquidity friction. Unlike properties valued under $5 million, which benefit from mortgage financing depth and broad buyer liquidity, ultra-prime estates depend almost entirely on all-cash buyers or specialized private banking credit facilities.
[Asset Value > $50M] ──> [Narrow Buyer Pool] ──> [Extended Holding Periods] ──> [Capital Reallocation Pressure]
This structural limitation dictates that pricing strategy is often an experiment in market depth testing. Sellers at this level do not price assets based on immediate liquidity needs; they price them to capture the marginal billionaire whose utility curve aligns precisely with the property's specific attributes at that moment in time. When macroeconomic conditions shift or capital flight accelerates toward alternative tax structures, holding periods lengthen, and pricing adjustments become tactical instruments rather than concessions.
Portfolio Rebalancing and Geographic Arbitrage
The decision to liquidate high-value residential holdings is fundamentally an exercise in asset class rotation. Billionaires maintain real estate portfolios as non-correlated holdings within a broader wealth management strategy. However, regulatory shifts, tax policy modifications, and lifestyle re-evaluations change the net present value of maintaining legacy compounds.
When an asset of this scale enters the market, it signals an adjustment in the owner's geographic risk assessment and liquidity preference. The transaction value of $57 million functions as a price discovery mechanism for an illiquid asset class undergoing macroeconomic pressure, demonstrating that even at the summit of the residential market, capital velocity ultimately supersedes sentiment.