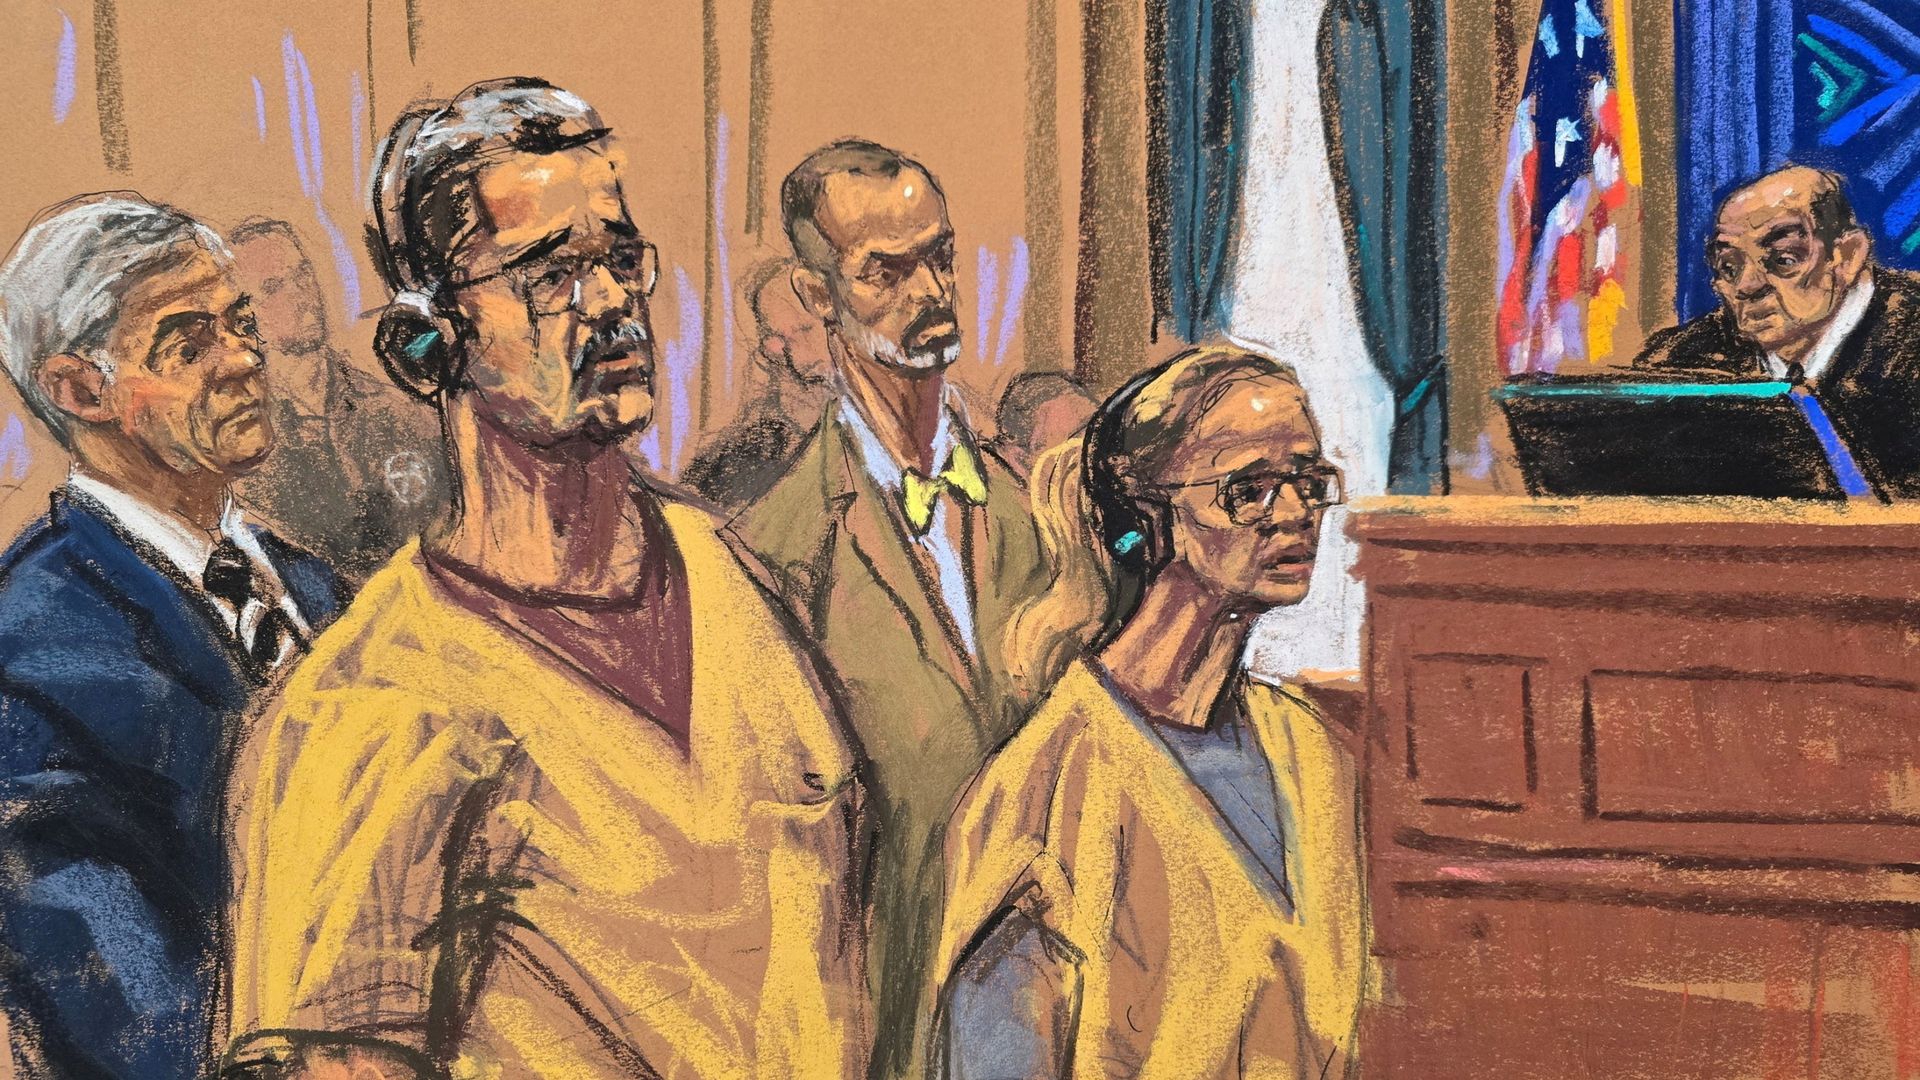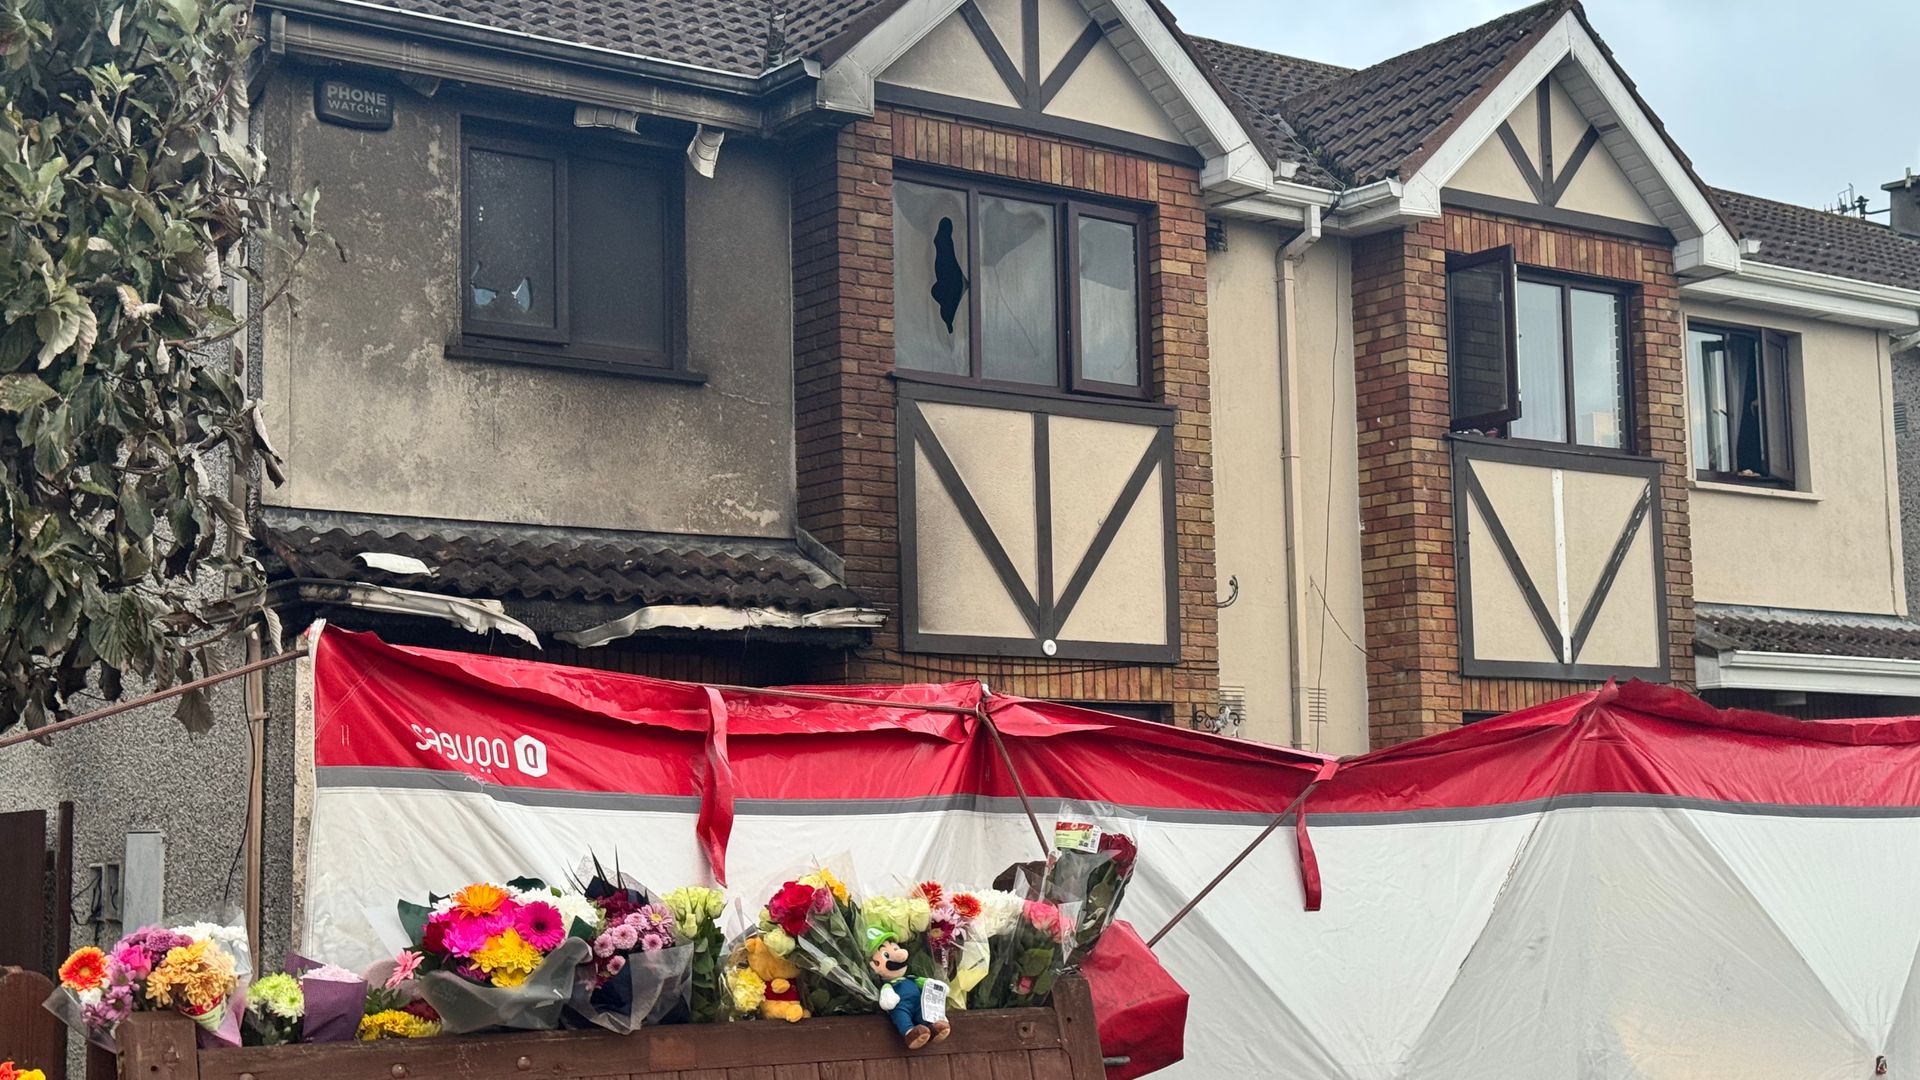
Moralizing consumer drug use after a fatal arson attack misdiagnoses a structural enforcement failure in illicit credit markets. Following the October 2026 Waterford house fire that killed Philip English, Kim English, and two of their children—with public discussion pointing to a drug debt dispute—Irish Justice Minister Jim O'Callaghan argued that illegal drug users fund such atrocities through their purchasing behavior. That framing treats a complex political-economy problem as a simple retail demand issue. To build an effective response, policymakers and analysts must separate consumer demand from predatory credit enforcement, map the incentives driving extreme violence, and evaluate interventions by their operational mechanics rather than political urgency.
Deconstructing the Competitor Narrative
Standard breaking-news coverage of the Waterford tragedy centers on three linked claims: a high-severity criminal event occurred, arrests and investigative activity followed, and senior officials or commentators linked the violence to the illicit drug trade and personal drug consumption. From a strategic analysis standpoint, that narrative compresses distinct causal layers into a single moral equation.
The first analytical gap lies in conflating spot-market consumption with credit-default enforcement. A casual or recreational buyer who pays cash for a small quantity participates in the lower tier of illicit distribution, generating revenue for dealers. Extreme domestic and neighborhood violence—such as arson targeting a family home over alleged unpaid balances—typically arises from credit extension, reputational signaling, or turf disputes within distribution networks rather than from a single retail transaction. Blaming every consumer collapses distinct behavioral mechanisms into one broad indictment.
The second gap involves institutional accountability versus individual culpability. When a justice minister urges citizens to examine their personal drug use in the wake of a lethal attack, the message shifts strategic pressure onto retail buyers. State enforcement capacity, financial investigation, witness protection, and community policing sit in a separate operational domain. Treating retail demand reduction as the primary lever for stopping retaliatory violence leaves the enforcement incentives of criminal suppliers intact.
The third gap is temporal compression. News reports naturally focus on immediate shock, custody timelines, and political reactions right after the fire. Structural intimidation rarely begins on the day of a fatal attack; threats, property damage, and debt transfer across relatives often accumulate over weeks or months. Without mapping that progression, observers mistake a culminating atrocity for an isolated outbreak.
Known Facts Versus Analytical Hypotheses
Rigorous policy analysis requires separating verified public facts from structured hypotheses about underlying mechanisms.
Verified Public Facts
- Four members of the English family—Philip English, Kim English, and two children, Callum and Jayden—died in a fatal arson attack in Waterford City in October 2026, with other family members injured and hospitalized.
- Justice Minister Jim O'Callaghan stated publicly that people taking illegal drugs support and fund horrific events seen in Waterford, while noting active Garda investigation progress and arrests.
- Public commentary and political debate around the tragedy—including statements by family members regarding an alleged drug debt and parliamentary and local calls by figures such as David Cullinane, Matt Carthy, and Fionán Bradley—highlighted drug debt intimidation as a pressing threat to families.
Analytical Hypotheses and Structural Mechanisms
- Hypothesis 1 (Reputational Signaling in Unlawful Credit): Because illicit drug suppliers cannot use civil courts or legal collateral to collect debts, violent retaliation functions as a credibility mechanism. Inflicting severe harm on a debtor or a debtor's relatives signals to other borrowers that non-payment carries catastrophic cost, even when the absolute euro value of a disputed debt appears small relative to human life.
- Hypothesis 2 (Asymmetric Risk Transfer to Families): When a primary borrower defaults, becomes incarcerated, or loses solvency, local debt collectors frequently shift collection pressure onto parents, partners, or siblings who lack direct involvement in drug distribution. Household members become high-leverage targets because of emotional bonds and predictable routines.
- Hypothesis 3 (Under-Reporting Trap): Victims of drug debt intimidation face a dual barrier to contacting authorities: fear of escalating retaliation from local actors and fear of self-incrimination or social stigma tied to illicit substances. Low reporting rates mask true prevalence and starve police of early-warning intelligence.
The Three Pillars of Drug Debt Intimidation
To understand why communities experience sudden spikes in severe intimidation, analyze the system across three structural pillars: Credit Mechanics, Enforcement Monopoly, and Information Silence.
Credit Mechanics
Street-level and mid-level drug markets rely heavily on informal credit—often termed "tick" in Irish and British street parlance—to expand sales volume among buyers with irregular cash flow and to recruit low-level couriers or runners. Credit lowers immediate friction to purchase or distribute, yet it creates balance-sheet exposure for the supplier. Once credit is extended without legal recourse, collection risk rises sharply during economic strain, addiction spirals, or supply disruptions.
Enforcement Monopoly
In any market lacking state contract enforcement, private violence substitutes for legal remedies. Mid-level or local operators maintain dominance by ensuring their threats are viewed as credible. Escalating from verbal warnings to window smashing, vehicle damage, or arson raises the perceived expected cost of default across the entire local borrower pool. Even rare extreme attacks exert outsized deterrence because observers update their risk estimates upward.
Information Silence
Intimidation thrives where reporting costs exceed perceived protection benefits. A family threatened over a relative's debt may calculate that going to the Gardaí triggers immediate reprisal before protective measures take effect, or that reporting exposes a loved one to criminal prosecution. When silence prevails, criminal actors face low detection risk during the intimidation phase, allowing coercive behavior to escalate unchecked until a critical incident occurs.
Cause-and-Effect Chains Missed by Surface Commentary
Surface commentary often treats drug violence as a linear chain: more drug users equals more money for gangs equals more crime. In practice, several non-linear feedback loops drive extreme harm.
First, debt escalation outpaces principal. Fees, interest-like markups, and punitive penalties added to an initial drug tab can turn a manageable sum into an insurmountable obligation. As the balance grows beyond a debtor's ability to pay, coercive tactics intensify because the supplier perceives total loss of the claim.
Second, local turf and status competition amplify cruelty. Criminal actors operating in tight-knit urban or regional towns do not act purely as profit maximizers; they also defend status and territory. A perceived slight or public defiance over a debt can trigger disproportionate retaliation to reassert dominance over rivals and borrowers alike.
Third, reactive crackdowns without victim insulation can displace harm. If enforcement arrests street dealers abruptly without parallel support for indebted families, unpaid balances do not vanish; rival actors or upstream collectors may step in to claim the debts, leaving vulnerable households exposed during the transition.
Tactical Intervention Sequence
Addressing drug debt intimidation requires sequencing operational actions so intelligence improves before enforcement disrupts local networks.
- Establish confidential, non-punitive intake channels. Expand dedicated reporting pathways—building on models such as Garda intimidation reporting and community support frameworks—that prioritize family safety and clearly separate victim protection from routine minor possession prosecution.
- Deploy rapid threat-assessment and target-hardening. When a family reports credible intimidation, pair local policing with practical physical security measures, safe-relocation options where warranted, and coordinated support services rather than treating the report as low-priority background intelligence.
- Run parallel financial and network investigations. Link intimidation reports to broader organized-crime and financial investigations so investigators trace who holds the debt ledger, who benefits from coercive collection, and where proceeds move.
- Coordinate multi-agency family support. Combine Garda liaison officers with local youth, addiction, and family support agencies so households under pressure receive financial counseling, legal guidance, and mental health support without navigating fragmented bureaucracies.
- Track operational metrics beyond seizure totals. Measure program performance using intimidation report-to-action response times, repeat-victimization rates, disruption of known debt-collection enforcers, and community trust indicators rather than relying solely on headline drug seizures.
Operational Limitations and Trade-Offs
No single intervention eliminates drug debt intimidation in the short term. Expanding confidential reporting carries an operational risk: if victims come forward and perceive slow police response or inadequate discretion, trust erodes faster than if no outreach had occurred.
Similarly, aggressive enforcement against mid-level distributors can create short-term market instability. When a supplier is removed, debt ledgers and territory can become contested, occasionally sparking retaliatory disputes unless enforcement is paired with sustained local presence and community intelligence.
Finally, public messaging faces a credibility trade-off. Warnings to consumers about funding criminal networks may resonate with citizens seeking moral clarity after a tragedy, yet over-relying on consumer appeals risks substituting rhetoric for hard operational reforms in policing, witness protection, and addiction treatment access.
Strategic Recommendation
Treat drug debt intimidation as a coercive credit and community-security failure governed by a dedicated multi-agency task force in high-risk areas, backed by ring-fenced funding for rapid family protection, financial disruption of debt collectors, and transparent quarterly reporting on response times and repeat victimization.